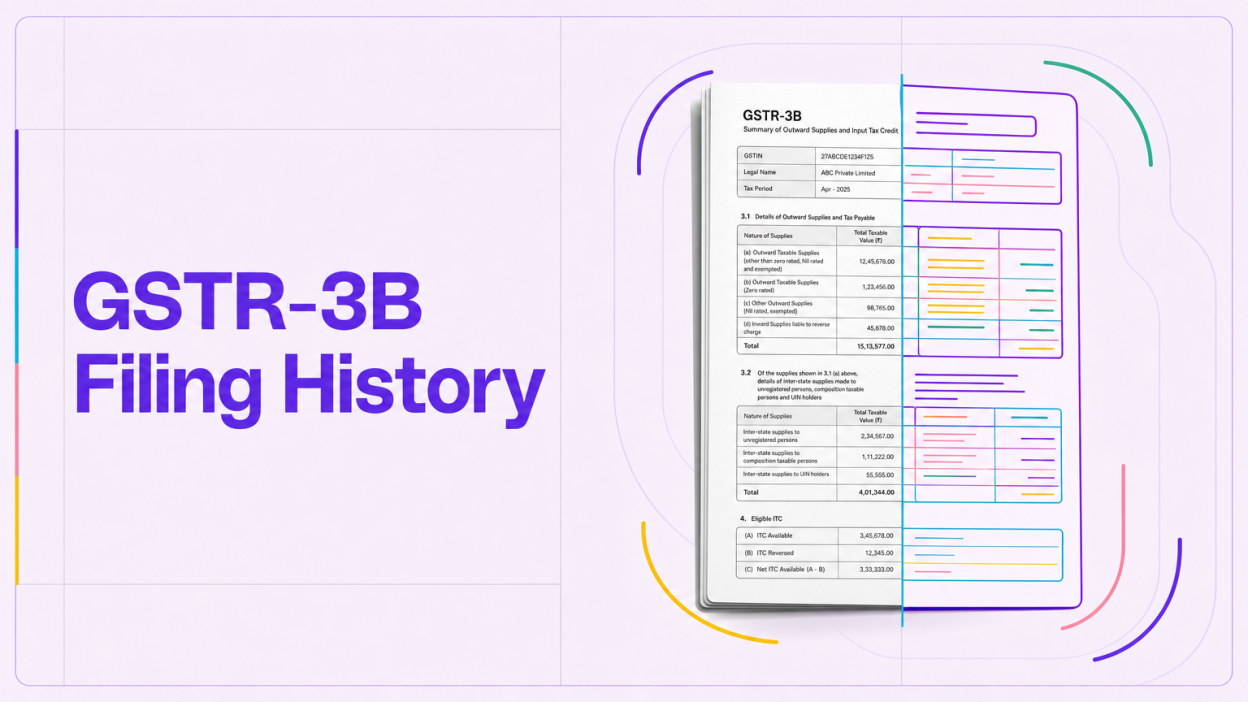
GSTR-3B is the summary GST return in which a registered business self-declares its outward supplies, input tax credit and tax paid for each period. Because it is filed monthly or quarterly and cannot be revised, its filing history gives lenders a time-stamped record of how regularly a business trades, reports and pays tax.
Many MSME borrowers in India lack audited financials a credit officer can rely on. What many do have is a GSTIN and years of returns.
That trail is underused. Teams often check that a GSTIN is “Active” and move on, when the period-wise record says far more about discipline and cash flow. This guide explains what the return contains, how the 2025 changes made it a firmer data source, and how to read filing history without overreading it.
What is GSTR-3B?
The GST Portal describes Form GSTR-3B as “a simplified summary return” through which taxpayers declare summary GST liabilities for a tax period and discharge them. Normal and casual taxpayers are required to file it.
What the main tables contain
| Table | What it captures | Why a lender cares |
|---|---|---|
| 3.1 | Outward taxable, zero-rated, exempt, nil-rated and non-GST supplies | Declared sales, the closest proxy for turnover |
| 3.2 | Inter-state supplies to unregistered persons, composition taxpayers and UIN holders | Geographic and customer mix |
| 4 | Input tax credit availed, reversed and ineligible | Purchase intensity and margin structure |
| 5 / 5.1 | Exempt inward supplies; interest and late fee | Evidence of past delays |
| 6 | Payment of tax, split by cash and credit | Real cash outflow towards tax |
GSTR 3B filing frequency and due dates
Monthly filers submit the return by the 20th of the following month. Taxpayers under the Quarterly Return Monthly Payment (QRMP) scheme, available to businesses with aggregate turnover up to ₹5 crore, file quarterly by the 22nd or 24th of the month after the quarter, depending on their state.
The GST Portal FAQ is explicit that the return “once filed cannot be revised.” Corrections flow into later periods, so each filing is a fixed, dated statement.
GSTR-1 vs 3B: why the difference matters to a lender
GSTR-1 is the invoice-level statement of outward supplies. GSTR-3B is the summary return that actually discharges tax. One tells the system what was sold; the other tells it what the business accepts as liability and pays.
A business can file GSTR-1 on time and delay the summary return because it lacks the cash to pay. That gap is one of the earlier stress indicators available to a lender.
Persistent differences between sales in GSTR-1 and liability in the summary return have historically pointed to either poor bookkeeping or under-reporting. Both matter to credit.
How the 2025 changes made GSTR-3B a firmer data source
Three GSTN measures in 2025 changed how much weight the return can bear.
Hard-locking of auto-populated liability
Through an advisory dated 7 June 2025, GSTN stated that from the July 2025 tax period the liability auto-populated from GSTR-1, IFF or GSTR-1A would be non-editable. Corrections must now be made in GSTR-1A before filing.
The lock applies to outward liability. ITC in Table 4 remains editable, so it deserves closer scrutiny than sales.
Table 3.2 remains editable
In April 2025 GSTN proposed making Table 3.2 non-editable. A subsequent advisory of 16 May 2025 said the table would remain editable for the time being. Analysts should not assume every auto-populated field is locked.
Three-year time bar on filing
The Finance Act 2023 amended the CGST Act so that returns cannot be filed after three years from their due date. GSTN advisories in June 2025 confirmed enforcement on the portal from the July 2025 tax period, covering GSTR-1, GSTR-3B, GSTR-9 and other returns.
For lenders, a gap older than three years is now permanent. A business cannot quietly regularise a dormant history just before applying for credit.
Six GSTR-3B signals lenders should read
The value lies in the pattern across 12 to 36 periods, not any single return.
- Filing regularity. Count periods filed on time, late and not at all. A borrower with 30 of 36 returns on time reads differently from one with a cluster of recent late filings.
- Delay trend. Rising average days-late is more informative than the absolute figure. Interest and late fee entries in Table 5.1 corroborate it.
- Nil returns. Occasional nil periods are normal for seasonal businesses. Long nil runs followed by sudden high turnover can indicate a dormant GSTIN reactivated for a loan.
- Turnover consistency. Compare Table 3.1 turnover with GSTR-1 totals and with bank statement credits. Timing differences are expected; persistent, material gaps warrant questions.
- ITC intensity. The ratio of ITC claimed to output tax indicates margin structure. A trader claiming ITC close to its entire output liability every month, with little cash tax paid, fits a pattern seen in networks.
- Cash versus credit settlement. Table 6 shows how much tax is paid in cash. Steady cash payment is a modest positive signal of genuine operating liquidity.
None of these is a verdict on its own. Each becomes useful when another source corroborates or contradicts it. The broader set of works the same way.
A practical use case: an MSME working capital application
Consider an illustrative case. A distributor in Pune applies to an NBFC for a ₹25 lakh working capital line, declaring annual sales of ₹3.2 crore.
The credit team pulls 24 months of history. GSTR-1 was filed on time throughout. The summary return was on time for 18 months, then 25 to 40 days late in four of the last six, with interest in Table 5.1.
Table 3.1 turnover matches GSTR-1, so sales are credible. But cash tax paid in Table 6 has fallen while ITC utilisation has risen.
Read together, this is a genuine business under recent liquidity pressure, not a fraudulent applicant. The right response is a smaller limit, tighter monitoring and a review of outputs, rather than rejection.
Verifying GSTR-3B signals at scale for your business
Reading one borrower’s history manually is straightforward. Doing it for thousands of applications a month requires a defined workflow.
- Verify the GSTIN, legal name and trade name against the applicant’s PAN and declared entity.
- Confirm registration status and date, and whether the registration has ever been suspended or cancelled.
- Pull period-wise filing status for GSTR-1 and GSTR-3B covering at least 12 months, ideally 24 to 36.
- Compute on-time ratio, average delay, delay trend and nil-return runs.
- Reconcile declared turnover against bank credits and, where available, consented GST return data.
- Cross-check the business against MCA, Udyam and digital footprint data to confirm it operates where and how it claims.
- Route exceptions to a credit analyst with the specific signal that triggered the referral.
Where BeFiSc fits: BizCheck returns a business risk report in about 60 seconds, combining GST, MCA, Udyam and digital footprint data so credit teams can see a GSTIN’s status alongside the entity’s corporate and MSME records in one view. Start with a free BizCheck report on a live application.
Limits and misconceptions
GSTR-3B is a self-declaration. The hard-lock improves consistency with GSTR-1, but it does not prove that the underlying invoices reflect real goods or services.
Filing history does not replace cash flow analysis. Informal debt never appears in GST data.
Exempt sectors and businesses below the registration threshold generate thin GST data. A weak trail is not, by itself, negative for those segments.
System fields also change. The March 2026 GSTN advisory on re-computing interest in Table 5.1 shows that calculated values can be corrected later, so read interest entries as indicative.
Key Takeaways
- GSTR-3B is the self-assessed summary return that discharges GST liability; it cannot be revised once filed.
- From the July 2025 tax period, auto-populated outward liability is hard-locked, while ITC in Table 4 and Table 3.2 remain editable.
- Returns older than three years from their due date can no longer be filed, so historic gaps are now permanent.
- The most useful credit signals are filing regularity, delay trend, nil-return runs, turnover consistency, ITC intensity and cash settlement.
- GST signals work best when reconciled with bank statements and entity data from MCA and Udyam.
Frequently Asked Questions
Does late GSTR-3B filing mean a business is a bad credit risk?
Not on its own. A recent cluster of delays with rising interest entries is a stress signal, but weigh it against bank statement behaviour, seasonality and the borrower’s explanation.
How can a lender check a business’s GST filing status?
The GST Portal’s public taxpayer search shows registration details and return filing status for a GSTIN. At scale, lenders use verification APIs and consented data to pull period-wise history into decision engines.
What is the GSTR-3B due date?
Monthly filers must file by the 20th of the following month. QRMP taxpayers file quarterly by the 22nd or 24th of the month after the quarter, depending on their state. The government can extend dates by notification.
What is GSTR-3B in simple terms?
GSTR-3B is a summary GST return in which a registered business reports its total sales, input tax credit and tax payable for a month or quarter, and pays that tax. It is self-assessed and cannot be revised after filing.
Conclusion
GSTR-3B has become one of the more dependable public signals on Indian MSMEs. The 2025 hard-lock, the three-year time bar and the return’s non-revisable nature give lenders a dated record that is hard to retrofit.
The opportunity is to read that record as a pattern, reconcile it against cash flow and entity data, and reserve analyst time for cases where signals conflict. Done well, this approves more genuine MSMEs while catching dormant and manufactured profiles.