When a company opens an account, applies for a loan, or joins a payments platform, the entity on the form is rarely the whole story. Behind it sit people who own it, control it, or benefit from it. Anti-money laundering rules require regulated entities to find those people.
That task, identifying the ultimate beneficial owner (UBO), is where many KYB processes are weakest. Ownership chains can run through several companies, trusts, and partnerships, and control can exist without much ownership at all.
This guide explains the Indian legal definition, the thresholds that apply to each entity type, how UBO under PMLA differs from SBO under the Companies Act, and how to build a verification process that holds up.
What a Beneficial Owner Is
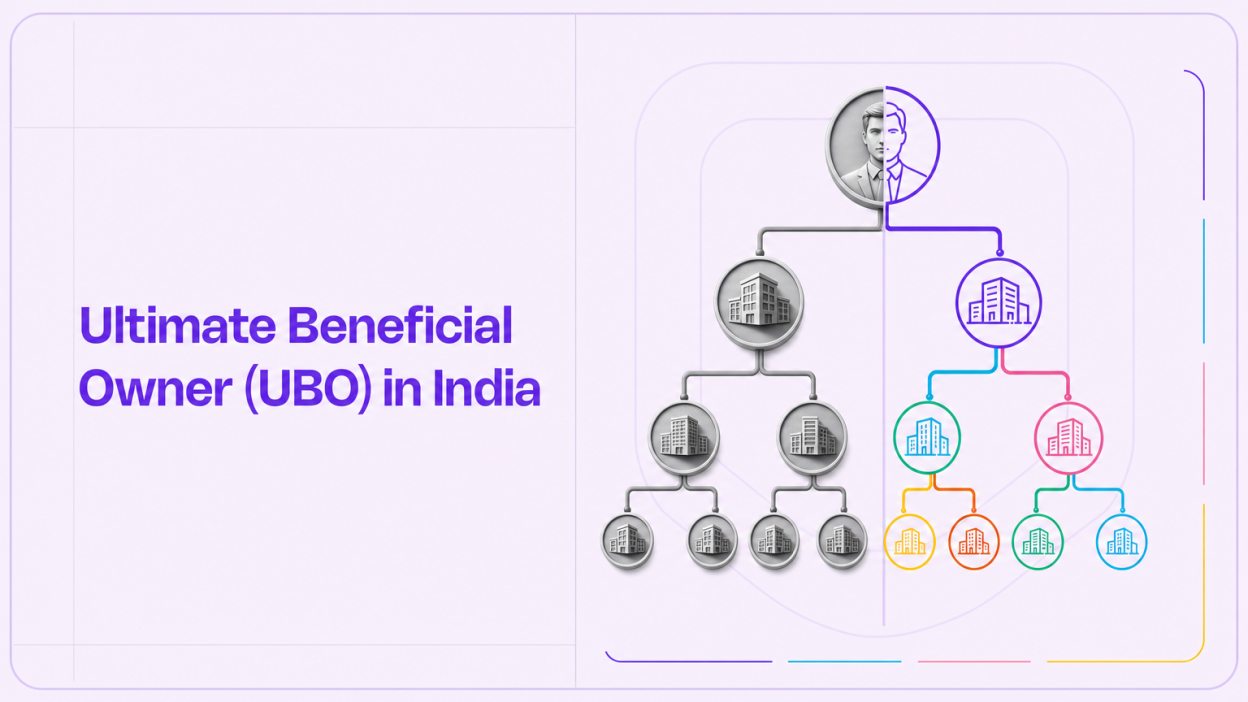
A beneficial owner is the natural person who ultimately owns or controls a customer, or on whose behalf a transaction is carried out. The key word is natural: a holding company is never the final answer. The chain continues until it reaches individuals.
Ownership and control are separate tests. A person with 5% of shares but the right to appoint most of the board is a beneficial owner by control, even though they fall below any ownership threshold.
Thresholds Under the PML Rules
The PML (Maintenance of Records) Rules, 2005 set the tests, which were tightened in March 2023.
| Customer type | Ownership test | Control test |
|---|---|---|
| Company | More than 10% of shares, capital or profits | Right to appoint majority of directors, or control management or policy decisions, including through shareholder or voting agreements |
| Partnership firm | More than 10% of capital or profits | Control through other means |
| Unincorporated association or body of individuals | More than 15% of property, capital or profits | Control through other means |
| Trust | Author or settlor, trustees, beneficiaries with 10% or more interest | Any natural person exercising ultimate effective control, including through a chain of control or ownership |
Where no natural person can be identified through ownership or control in a company, partnership or association, the relevant natural person who holds the position of senior managing official is treated as the beneficial owner.
Companies listed on a recognised stock exchange in India, or in notified jurisdictions, and their majority-owned subsidiaries are exempt from identifying individual shareholders as beneficial owners, because listing brings its own disclosure regime.
UBO Under PMLA vs SBO Under the Companies Act
India has two beneficial ownership regimes that overlap but are not the same.
| Aspect | Beneficial owner (PMLA) | Significant beneficial owner (Companies Act) |
|---|---|---|
| Purpose | Customer due diligence by regulated entities | Company disclosure to the Registrar |
| Who identifies | The bank, NBFC or other reporting entity | The company itself |
| Threshold for companies | More than 10% ownership, or control | 10% or more through indirect holdings, or significant influence or control |
| Where recorded | The RE’s KYC records | Company’s register and filings with the Registrar (Form BEN-2) |
SBO filings are a useful starting point, but a regulated entity cannot simply copy them. It must reach its own conclusion under PMLA, verify identities, and document how it traced ownership.
How to Identify Beneficial Owners Step by Step
- Collect the ownership declaration: Ask the customer for a shareholding or partnership structure chart down to natural persons, signed by an authorised signatory.
- Pull registry data: Retrieve company master data, directors and charges from MCA records; check GST registration for trade names and addresses; retrieve legal-entity CKYC where available.
- Trace each layer: For every corporate shareholder above the threshold, repeat the process until natural persons are reached. Multiply percentages through the chain to find indirect holdings.
- Control test: Review articles of association, shareholder agreements and board composition for appointment rights and vetoes.
- Apply the fallback: If no individual meets the tests, identify the senior managing official and record why.
- Document the conclusion: Keep the structure chart, sources, and reasoning on file.
Verifying the People You Identify
Identification names the people. Verification proves they are who the declaration says.
- Identity: OVD-based KYC and PAN verification for each beneficial owner.
- Director cross-check: Confirm DIN and directorships through MCA data; people with many directorships in recently formed companies deserve questions.
- Screening: Check each beneficial owner against sanctions lists and politically exposed person (PEP) data, and for adverse media.
- Consistency: Compare names, addresses, and contact details across declaration, registry data, and KYC documents.
Risk should drive depth. A simple, domestically owned private company needs less than a multi-layer structure with offshore holding companies.
Common Red Flags
- Ownership chains with offshore entities and no clear business reason
- Nominee shareholders or directors with no apparent connection to the business
- Frequent changes in shareholding or directors shortly before onboarding
- Beneficial owners who share addresses or contact details with many unrelated companies
- Reluctance to provide shareholder agreements or complete structure charts
- Holdings sitting just under the threshold across several family members
The last flag matters because splitting ownership to stay under 10% does not defeat the control test, and it can itself be a sign of concealment.
Use Cases
Current account opening: A bank onboarding a private limited company retrieves MCA data, traces a 60% corporate shareholder to two individuals, verifies both with PAN and OVD, and screens them before activation.
B2B lending: An NBFC lending to an MSME identifies a silent partner with a 30% profit share from the partnership deed and includes that person in KYC and guarantee discussions.
Payment aggregator merchant onboarding: A PA flags a merchant whose sole director holds directorships in 40 recently incorporated companies and moves it to enhanced due diligence.
Trust account: A bank identifies the settlor, trustees and beneficiaries with 10% or more interest, and a protector with power to replace trustees, before opening an account for a private trust.
Key Takeaways
- A beneficial owner is always a natural person who owns or controls the customer.
- PMLA thresholds: more than 10% for companies and partnerships, more than 15% for unincorporated associations, 10% or more for trust beneficiaries, plus control tests.
- PMLA beneficial ownership and Companies Act SBO are separate regimes; use SBO data as input, not as the conclusion.
- Trace every layer, test for control, and document how the conclusion was reached.
- Verify and screen every beneficial owner, with depth scaled to structural risk.
Frequently Asked Questions
What is the difference between UBO and SBO?
Regulated entities under PMLA identify UBO for customer due diligence. SBO is declared by companies under the Companies Act to the Registrar.
Do listed companies need UBO identification?
Companies listed in India or in notified jurisdictions, and their majority-owned subsidiaries, are exempt from identifying shareholders as beneficial owners.
Is a director always a beneficial owner?
No. Directors are identified separately. A director is a beneficial owner only if they meet the ownership or control tests, or are the senior managing official under the fallback rule.
What is the UBO threshold in India?
No. Directors are identified separately. A director is a beneficial owner only if they meet the ownership or control tests, or are the senior managing official under the fallback rule.
What is the full form of UBO?
Ultimate Beneficial Owner.
Conclusion
Beneficial ownership is where KYB becomes genuinely difficult. Registries give part of the picture, declarations give another part, and control often sits in documents that customers are slow to share. Regulated entities are expected to put these together, reach their own conclusion, and prove how they did it.
The institutions that do this well automate the data gathering and cross-checks, and reserve analyst time for the structures that genuinely need it.
BeFiSc’s business verification APIs pull company, director, GST, and PAN data into one flow, so beneficial ownership can be traced and verified faster. Talk to the BeFiSc team about your KYB workflow.